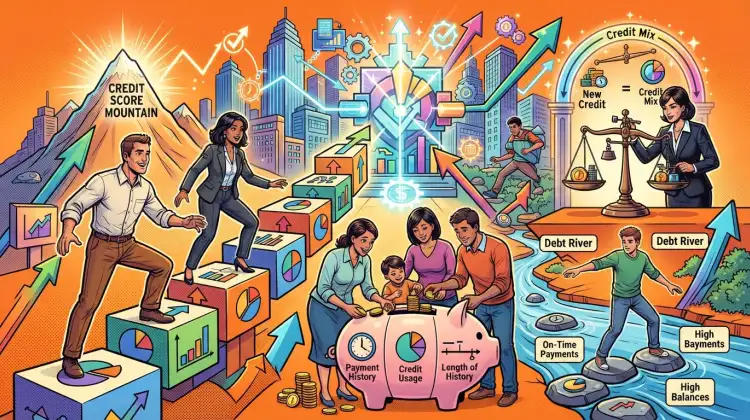
Your credit score is a three-digit number that lenders use to judge how likely you are to repay borrowed money. In the US, most scores range from 300 to 850, and the two dominant models are FICO and VantageScore. Understanding how credit scores are calculated helps you focus your effort where it matters most and avoid myths that lead to wasted time or unnecessary fees.
Here is how the math actually works, based on the published scoring criteria from FICO and VantageScore, and what you can do to protect your score over the long term.
The two scoring models you will encounter
FICO, developed by the Fair Isaac Corporation, is the most widely used scoring model in US lending. Mortgage lenders, credit card issuers, and auto lenders commonly pull FICO scores. VantageScore was created by the three national credit bureaus—Equifax, Experian, and TransUnion—as a competing model, and it is also widely used.
Both models draw on the same underlying credit reports, but they weight the data differently. That is why you can see different numbers depending on which score a lender pulls. Neither model is inherently better; they are simply different formulas applied to the same raw information.
The FICO score breakdown
FICO publishes the approximate weightings used in its base score. These percentages apply to the general population, and they can shift for people with thin credit files or specific loan types.
- Payment history (35%): The single largest factor. On-time payments help; late payments, collections, charge-offs, and bankruptcies hurt. A payment 30 days late is less damaging than one 90 days late, and the impact fades over time.
- Amounts owed (30%): This is largely about credit utilization—the share of your available revolving credit you are using. Lower utilization is generally better. Many experts suggest keeping it below 30%, and below 10% is even stronger.
- Length of credit history (15%): Older accounts help. Closing your oldest card can shorten your average account age and reduce your score.
- Credit mix (10%): A blend of revolving accounts (credit cards) and installment loans (auto, student, mortgage) can modestly help.
- New credit (10%): Each hard inquiry from a new application can ding your score slightly. Multiple inquiries in a short window for the same type of loan, such as rate shopping for a mortgage, are typically grouped and counted once.
How VantageScore differs
VantageScore uses a similar set of inputs but groups them differently. In its current models, payment history is still the most influential factor, followed closely by credit utilization and the balances on your accounts. VantageScore also considers how much you owe in total and how your balances have changed over time.
One practical difference: VantageScore can generate a score for consumers with very little credit history, sometimes after just one month of activity, whereas FICO typically requires at least six months of history. That makes VantageScore useful for people building credit for the first time.
What is not in your score
Federal law restricts what credit scoring models can use. Your score does not include your race, color, religion, national origin, sex, marital status, age, or whether you receive public assistance. It also does not directly factor in your income, employment history, or assets—though lenders may ask for that information separately when you apply for a loan.
How to use this information
Because payment history and utilization together account for roughly two-thirds of a FICO score, those are the levers worth pulling first. Set up automatic payments to avoid missed due dates, and pay down revolving balances before your statement closing date so a lower balance is reported to the bureaus.
Check your credit reports for free at AnnualCreditReport.com, the only federally authorized source for free weekly reports from all three bureaus. Dispute errors in writing, and be patient—improving a score is a months-long process, not a same-day fix.
What to remember
Credit scores are calculated from the data in your credit reports, weighted most heavily toward payment history and how much of your available credit you use. FICO and VantageScore use similar inputs with different weightings, so your score can vary by lender and model. Focus on paying every bill on time, keeping balances low relative to your limits, and monitoring your reports for errors. Those habits do more for your score than any quick fix.